 In the year 2022, what are the repercussions of being unable to make a payment on a payday loan?
Payday loans provide borrowers with a fast and simple solution to a variety of pressing monetary problems. You are able to receive quick cash with the use of this kind of unsecured loan, which allows you to pay bills, deal with a medical emergency, go grocery shopping, or repair your vehicle until you are paid again. It’s possible that people with poor credit who struggle to qualify for other kinds of loans may find these loans to be incredibly helpful.
The fact that it is not hard to get this form of short-term loan is a benefit; nevertheless, the interest rates are typically fairly high, which is a huge negative. The interest rates that payday lenders, as opposed to traditional financial institutions such as banks and credit unions, often impose on the loans that they issue are exorbitantly high. As a consequence of this, it is often challenging for individuals who get this sort of loan to be able to return it. Before you even think about applying for a payday loan, you should make sure you are informed of the consequences that will follow if you are unable to repay the money by the time it is due.
In the event that a payday loan is not repaid when it is due, what are some of the potential consequences?
When the borrower of a payday loan does to repay the money by the due date, the borrower is often subject to severe repercussions. When you borrow money from a different trusted lenders online, the most likely conclusion is that you will be charged extra fees or interest on top of the amount of money that you borrowed.
Lenders of payday loans will often want access to your bank account so that they may deduct the amount of the loan payment from the remaining balance on the due date. A nonsufficient funds fee will be applied to your checking account if a payday loan provider tries to withdraw money electronically from your checking account but is unable to do so owing to insufficient funds (NSF).
The specific fee that will be levied against you if you are unable to repay a payday loan may vary from state to state. Additionally, interest will continue to build on your loan during that time period, adding to the debt trap that is caused by payday loans. In addition, failing to make a payment on a payday loan might have a negative impact on your credit score. This would make it more difficult for you to get a loan in the future from the same company that provided the payday loan like ACFA-Cashflow.
What Are The Consequences Of Going Into Default On A Payday Loan At The Same Time That You Close Your Bank Account?
Though you do not pay back a payday loan by the due date and also close your bank account, the payday lender will try to get in touch with you in an effort to compel you to refund the money that you borrowed even if you have closed your account. If, after about sixty days of using this approach, it is determined that it is not effective, your account will be sent to a third-party debt collector.
These companies have a well-deserved reputation for harassing payday loan debtors in an aggressive manner in order to collect money that is owed on payday loans. They will continue to communicate with you and write you letters until either the money is repaid or an arrangement is reached with the company that provided you with the payday loan. Giving your personal information to a debt collector will not only have a bad impact on your credit history but will also make it more difficult for you to qualify for fresh payday loans in the future.
How much time must pass before the borrower is considered to be in default on a payday loan?
The length of time it takes to default on a payday loan may vary from one payday lender to the next when the borrower is working with many payday lenders. However, the lender will often offer you a grace period of sixty days from the date that was originally due pursuant to the agreement for the payday loan before labeling you as a defaulter. This grace period begins on the day that the loan was first due. Following the expiration of this grace period, the details of your payday loan debt will be reported to a collection agency in an effort to retrieve the money that is owed.
You run the risk of receiving a jail term if you are unable to repay the payday loan that you took out.
Even if you are already behind on payments, payday loan collectors are not allowed to threaten you with jail time, and you are not allowed to go to jail for failing to repay a payday loan. Payday loans are not federally insured. On the other hand, they may choose to file a civil complaint against you and bring the matter before a judge. The state in which you reside will be the one to decide whether or not you will suffer any legal penalties as a result of the actions you have taken. Your wages might be garnished, or a lien could be put on your property, depending on the circumstances of the situation.
Conclusion
In the event that you are unable to return your payday loan on the date that was previously agreed upon, the appropriate move for you to do is to get in touch with the payday lender who provided you with the loan. In most circumstances, they should be able to devise a reasonable strategy for the management of your debt that you can adhere to. Some states let customers consolidate their debt by taking out loans, while others do not.
If you close your bank account or fail to meet your financial responsibilities, you may be subject to hefty NSF charges, a reduction in your credit score, and problems with debt collectors. You may have a tough time acquiring future loans if you do not take steps to restore your credit. If you believe that the interest rates and fees associated with payday loans are exorbitant, you may choose to investigate the other personal loan alternatives available on ACFA-Cashflow or submit an application for a loan at the credit union in your area instead.
Author bio
Cathy Pamela Turner
Personal Finance Writer at ACFA Cashflow
Cathy Pamela Turner has extensive expertise in banking, finance as well as accounting. A large portion of her experience was spent within commercial banks, where she worked in the roles of an underwriter credit Risk Policy Manager, director of credit risk, chief credit executive, and many more. Throughout her banking career Cathy not only reviewed different kinds of commercial and personal loans, but also created and monitored policies about the origination of these loans and how they were controlled.
 Have you exhausted all of your money means yet still need to satisfy an urgent need? When you’re struggling to make ends meet, it’s easy to get depressed and assume there’s no way out.

 Brady left the NFL with a skip in his step, even though his last season was not one in which he took home the Super Bowl. He still knew he had spent many years manipulating the
 We provide you and every other loyal client a $500 loan right now. We provide a $500 loan that is available immediately and does not need a credit check. If you reside in the United States, Bridge Payday will offer you money the same day. All you have to do is complete a brief online application and provide the required documentation.
 During business travel, professionals experience significant levels of stress and can develop harmful habits. Plan ahead and stay productive and healthy on your trip. Travel-related stress can have a negative impact on work performance and cause employees to become distracted from their tasks.
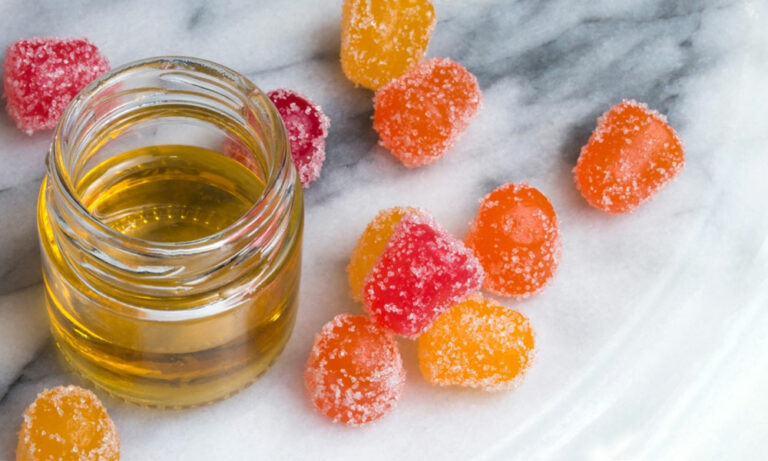
 CBD shows promising results in easing various conditions. Preliminary research and feedback from consumers reveal that the cannabinoid may help with wellness issues like pain, anxiety, depression, and insomnia. The market offers a wide range of CBD products to use, and CBD oil and gummies are the most popular options. They come in different potencies to ensure every user gets the CBD strength they need. Below is a guide comparing CBD oil vs gummies to help you decide which product to utilize for relief.
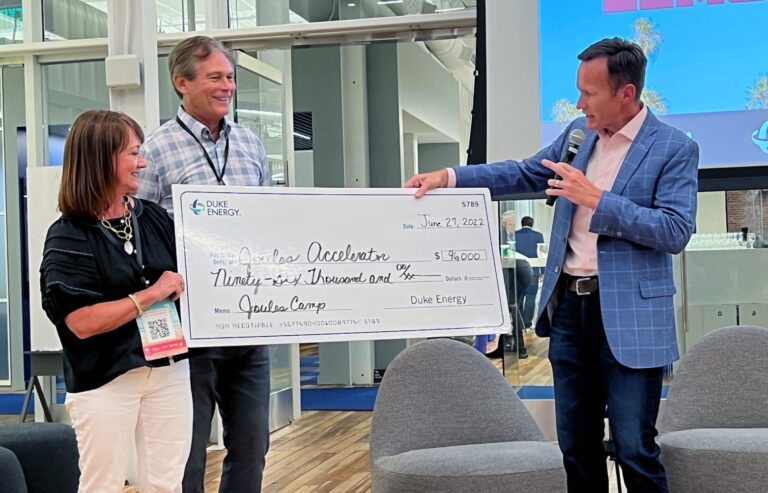
 The Duke Energy Foundation will fund a program that will allow college students to help energy startups – working with local neighborhoods to bring decarbonization programs to underserved communities in the Carolinas.
 Charlotte’s own