How to Become a Casino Dealer

0

People take advantage of the entertainment from YouTube videos, social media platforms, and online games that include gambling or sports betting. As a result, the gambling market has started to rise again in 2021, with a market size of 230.86 in US dollars. So, there’s a signal that for the next coming years, as the pandemic eases, new career paths will open, especially for the job of a casino dealer.
So, who is a casino dealer? Casino dealers are the masters of the game. The word “master” means that they have undergone beating the odds and setting the vibe of casino games to captivate a huge number of gamblers.

It’s easy to call them the experts in terms of casino setups, but the truth is, it’s not simple to become a casino dealer. So, if you’re the person who wants a shift in your career, this position could be a good head start to your liking. And there are a lot of lessons and tricks to learn to become one.

Casino gambling is a challenging task. It requires interest to learn. Although the applicant doesn’t need to have long years of experience, what matters is the willingness to learn, and here’s how.

Participate in Training Programs or Dealer Schools

It takes full concentration, accuracy, speed, and confidence to become a casino dealer. There’s a need to attend vocational courses or undergo on-the-job training from accredited dealer schools. But, if anybody finds this requirement too sunken, then it’ll be chaos stepping into a career that is totally alien to you.

There are courses that give adequate training and solid ground on how to play casino games as well. Instructors let you play poker, roulette, blackjack, baccarat, etc., to discover strategies for you to learn and apply. And they will guide you through the standards from the perspectives of casino operators and clients.

This opportunity makes you feel like you’re already at a game table, arranging chips and preparing cards with no head down. After 2 to 3 months of training, a certificate is awarded by the school as a testament to one’s competency.

Here’s a list where you can enroll for a gaming-hospitality and dealer course:

  • The University of Nevada at Las Vegas
  • Boston University
  • University of Macau
  • Plato Education Services: Casino Staff Training Center
  • UNLV Boyd School of Law
  • Cerus Casino Academy

Be a Math Wizard

Always be ready with math moments on bet sizes. And yes, casino games require a skilled mathematician because of the complexity of the rules.

It’s not always about the games themselves and how they are played. One must know how to calculate the probabilities of either winning or losing and what type of card does the opponent is holding. But it doesn’t stop on computations. Casino dealers memorize every count and amount at the same time from different tables. And doing this every day at training will help sharpen one’s mathematic skills.

Get Licensed

The gambling industry is also strict with licensing not only for the land-based and online casino operators but also on employees like casino dealers. There are requirements to provide depending on the state you’re living. So, it’s best to know and comprehend rules and regulations on licensing.

Aside from having the proof of eligibility to be a dealer in a gambling den, you need to let the officials in charge for the background check, proof of identity and settle some licensing fees required by your state or government.

Flexible Working Skills

Multi-tasking involves speedy calculations, execution of rules, mechanical skills, and outstanding customer service. These factors are seen from other careers that are also applicable to being a casino dealer.

Having enough knowledge of the rules of the casino and the games will develop the integrity of the business. That’s why you should pay attention to classes to learn shortcuts and secrets that conceive pros and successful casino gamblers.

Aspiring casino dealers should watch out for interpersonal communication because this is also one of the best attributes to maintain the ambiance of a casino game. It’s crucial working in casinos because gamblers are involved with a concentration on how the game will turn out whether they bluff or not. Always take note of the small details to avoid getting involved with business issues.

As an example, some gamblers will tend to say words that will trigger their opponent’s focus until such time they’d get annoyed with each other. So, what are you going to do next?

Get the Job

After getting licensed and learning tips and tricks that will create a lucrative career path in the gambling industry, it’s time to get the job. Apply online or visit casino houses and be the best version of yourself. There is no harm in trying a casino dealer position because opportunities can come from anywhere!

Workers’ Compensation Claim: 4 Things Every First-Time Employee Should Know

0

Sustaining an injury or an illness at work can be scary and overwhelming. You often have no idea what steps to take and who to turn to for help after dealing with a workplace accident. Luckily, employees who get injured or become sick while working for their employer may be entitled to file a workers’ compensation claim. A workers’ compensation or workers’ comp is an insurance program giving injured employees or become ill in the workplace monetary assistance to cover their medical expenses and lost wages.   
However, if you’re a first-time employee, you should know that understanding a workers’ comp claim isn’t just knowing its coverage. Without proper knowledge about this matter, you may end up facing problems when you get injured and want to file a compensation claim.   

For a first-time employee like you, below are the four things you should know about a workers’ compensation claim:   

  • Filing A Workers’ Comp Claim Means Waiving Your Right To File A Lawsuit   

It is a thing a first-time employee like you should know about a workers’ comp claim. This type of claim intends to finance the medical costs and lost wages sustained due to the workplace injury or illness, regardless of who is at fault. Hence, when you decide to institute a workers’ comp claim, you lose your right to file a personal injury lawsuit to recover compensation. It means you can’t use both remedies simultaneously for your workplace injury.   

On the other hand, if you strongly believe that your injury is due to someone else’s negligence, filing a lawsuit in court is much better than filing a workers’ comp claim. It is because you can hold the at-fault party who can be your employer, colleague, or a third-person liable for your losses. But, when you consider pursuing a lawsuit, it’s best to hire a dedicated lawyer. In doing so, you need to familiarize yourself with how much does it cost to sue your employer. That way, you’re aware of the fees to pay, and you can ensure you’re not overwhelmed by the thought of filing a case.   
  • Specific Injuries And Illness Are Covered By Workers’ Comp Claim   

It’s crucial to understand that workers’ comp claim doesn’t cover all forms of injuries and illness. Generally, under the workers’ compensation program, employees who get injured while doing their job, whether onsite or offsite, are eligible to file a claim against the employer’s insurance provider. Aside from the work-related injuries, occupational diseases developed during an employee’s employment are also included in the coverage. Common occupational illnesses are carpal tunnel and any health issues caused by toxic chemical exposure.   

On the other hand, your workers’ comp claim will not be successful if your injury or illness complained of is included in the following exclusions:   

  • Self-inflicted injuries;  
  • Injured sustained due to fighting against another employee;  
  • Injured suffered while committing a crime, violating company policies, or under the influence of drugs.   

  • A Workers’ Comp Claim Doesn’t Compensate Non-Economic Damages   

Unlike a personal injury lawsuit, instituting a workers’ comp claim doesn’t allow you to recover non-economic damages or those which don’t have a specific monetary value. These can include pain and suffering, emotional distress, loss of enjoyment in life, and other similar situations. Since the workers’ compensation is limited only to medical and wage replacement benefits, filing a claim on the ground that you’ve experienced anxiety, depression, and pain and suffering may not prosper.   

Thus, if you want to get compensated for the full extent of your losses, including economic and non-economic damages, bringing a claim under the workers’ comp insurance program may not be the best option. But, to help you decide which legal course of action you should take after sustaining an injury at work, it’s best to consult a lawyer about your situation.   

  • The Injured Employee Should Report The Injury To The Employer   

Another thing you should learn about filing a workers’ comp is the injured employee should report the injury sustained as quickly as possible to the employer. Generally, reporting is one of the essential steps in the filing process. Failing to do so may adversely impact the claimant’s chances of winning the claim.   

Like the time limits you have within which you need to file your claim, you need to be wary of the deadline associated with reporting. In most cases, the deadline ranges from 30 days to 60 days, depending on what state you come from. Unable to notify your employer within the said period may not be favorable for your situation. Hence, when you’ve decided to file a workers’ comp claim, you should educate yourself about the reporting deadlines to ensure a successful outcome later.   

Bottom Line   

As a first-time employee, your confusion and lack of knowledge about the workers’ compensation claim are understandable. But, as you work for your employer, it’s essential to keep the information mentioned above in mind to understand workers’ comp and how it works. That way, you’ll know what to do should you get injured or become ill in the workplace.   


North Carolina Is 2022’s 4th Best State to Drive in

0

With traffic congestion costing U.S. drivers an average of 36 hours and $564 during 2021, the personal-finance website WalletHub today released its report on 2022’s Best & Worst States to Drive in.
To determine the most driver-friendly states in the U.S., the site compared the 50 states across 31 key metrics. The data set ranges from average gas prices to rush-hour traffic congestion to road quality.

Driving in North Carolina (1=Best; 25=Avg.):

  • 23rd – Share of Rush-Hour Traffic Congestion
  • 20th – Car Theft Rate
  • 9th – Auto-Repair Shops per Capita
  • 17th – Avg. Gas Prices
  • 7th – Auto-Maintenance Costs
  • 21st – Road Quality
  • 10th – Car Dealerships per Capita

Best & Worst Driving States

Overall Rank  State Total Score  Cost of Ownership & Maintenance  Traffic & Infrastructure  Safety  Access to Vehicles & Maintenance 
1 Iowa 62.04 5 7 38 22
2 Oklahoma 61.65 4 9 34 27
3 Kansas 61.51 12 4 36 32
4 North Carolina 61.27 7 29 23 10
5 Texas 60.57 25 41 14 4
6 Georgia 60.04 8 39 27 8
7 Wisconsin 60.03 3 19 37 20
8 Tennessee 60.02 1 26 41 21
9 Illinois 59.71 34 36 6 5
10 Indiana 59.46 14 22 31 17
11 Nebraska 59.46 16 6 35 33
12 Kentucky 59.42 6 23 26 31
13 Ohio 59.27 2 31 39 7
14 Virginia 58.45 9 40 29 13
15 Alaska 58.34 27 14 5 50
16 Alabama 58.25 10 16 40 26
17 Idaho 58.21 29 5 21 43
18 New York 57.82 42 46 3 2
19 North Dakota 57.80 22 1 45 47
20 Maine 57.73 24 17 16 37
21 West Virginia 57.25 11 20 32 44
22 Florida 56.71 31 44 17 3
23 South Dakota 56.65 18 11 44 38
24 Arkansas 56.35 21 10 42 34
25 Arizona 55.98 32 21 15 25
26 Utah 55.65 30 18 22 29
27 Vermont 55.62 33 24 8 40
28 New Mexico 55.60 28 3 43 42
29 Mississippi 55.41 17 12 47 35
30 Louisiana 55.24 35 25 12 30
31 Minnesota 55.11 26 32 25 19
32 Pennsylvania 54.68 38 33 28 6
33 South Carolina 54.62 13 27 46 28
34 New Hampshire 54.49 19 45 13 41
35 Oregon 54.41 44 13 18 23
36 Montana 53.95 20 2 50 45
37 Massachusetts 53.75 41 49 2 9
38 New Jersey 53.75 36 48 4 12
39 Connecticut 53.30 46 34 1 24
40 Nevada 53.11 45 15 10 39
41 Wyoming 52.31 15 8 48 48
42 Missouri 51.47 23 28 49 15
43 Michigan 51.40 43 30 30 11
44 Colorado 50.85 40 38 33 16
45 Washington 49.34 48 37 20 14
46 Maryland 48.54 37 50 19 18
47 California 48.00 50 42 9 1
48 Delaware 48.00 39 35 24 49
49 Rhode Island 47.41 47 47 7 46
50 Hawaii 41.02 49 43 11 36

Note: With the exception of “Total Score,” all of the columns in the table above depict the relative rank of that state, where a rank of 1 represents the best conditions for that metric.

Do you agree with the ranking? 

Mission Possible Grant Program helps Carolina Youth Coalition Launch Virtual Mentoring Program

0

Charlotte recently ranked in the top 10 in the nation for places where people are the most generous with their time and money, according to SmartAsset.com. With that in mind, it’s no surprise that Apparo’s Mission Possible Grant Award remains extremely popular among the Queen City’s nonprofit community.
This innovative grant helps nonprofits uncover ways to more efficiently and effectively position people to climb the economic ladder to transform their lives and the lives of their families. Many nonprofits need additional funding, but they also need a gentle hand-on-the-shoulder to offer guidance and insight. Mission Possible is one of the only local grants that provides nonprofits with both.

For example, last year’s Mission Possible winner, Carolina Youth Coalition, is launching a new virtual mentoring program called E-Fellows as a result of this technology-focused grant program. Today, Carolina Youth Coalition is able to deliver its youth mentoring program in an entirely different way and help more “fellows” than ever before.

Apparo and Accenture are currently inviting Charlotte-based nonprofits to dream big in the new year with this grant, offering unparalleled access to pro bono consultants who will take them on an ideation journey to envision how technology can solve their biggest challenges. They’ll coach nonprofits as they build a proposal for a technology-based solution that will maximize the organization’s work. And for one lucky organization, they’ll give $10,000 in cash and up to $50,000 of consulting support to make that dream a reality.

The grant is open to any nonprofit that supports economic opportunity and works to improve Charlotte’s 50 out of 50 ranking daily. With the right technology, this nonprofit could transform lives today and for future generations.

All nonprofits that meet the eligibility criteria are welcome to participate. There is no application process. Simply register for the 2022 program by Friday January 21 at 11:59pm by using this link: https://apparo.wufoo.com/forms/w12216191jxnusl

For more information, please visit Apparo.org.

Charlotte’s Midnight Diner Could Be Moving Uptown

0

This past November we reported that a $750 million 3-tower complex was going to be built where the popular Midnight Diner now stands.

We’ve now learned that the popular late-night spot may be getting a new home even closer to the heart of the city.

According to a new permit filed with the city’s planning department, the Midnight Diner’s owner Brian Dominick is attempting to rebuild the eatery on a .86 acre parcel next to the Spectrum Center at 420 E. Trade St.

What do you think about the new location?

HOW TO SAVE FOR A HOUSE

0

You should begin saving for a home as soon as you have the desire to do so. Most individuals understand that buying a home is likely to be the most expensive single purchase they will ever make. However, many first-time buyers misjudge the amount of money required to acquire their ideal house.
  1. MAKE A DECISION ABOUT YOUR BUDGET

Before you even start looking at houses, figure out how much you can comfortably pay. What the bank says you can afford may not be the same as what you can afford. Calculate your entire house costs, which include your mortgage, property taxes, and home insurance, which may frequently add hundreds of dollars to your total mortgage. Start investing at early stages of your life. Visit European brokers and get the list of options available. 

After determining how much house you can afford, you may determine how much you need for a down payment. A 20% down payment is ideal to avoid paying private mortgage insurance, which may quickly add hundreds of dollars to your mortgage. However, if you reside in a higher-cost-of-living location, like we do, and have a strong credit score (700 or more), you may probably still qualify for reasonable mortgage loans with at least a 10% down payment.

  1. PAY OFF YOUR CREDIT CARDS

Housing expenditures should never surpass one-third of your whole income, according to the general rule. However, if you have other obligations, such as a vehicle loan, school loans, or credit cards, the amount of money you may pay toward a mortgage may be limited. Consider paying off some of your debt first, which will not only relieve some of your financial stress but will also help you achieve a better mortgage rate. While it may seem paradoxical to pay down debt to save, after those bills are paid off, you might have hundreds, if not thousands, of dollars freed up that will allow you to save more quickly.

  1. FINANCE YOUR FUTURE MORTGAGE

We started living as if we were already paying that new mortgage for over a year before we bought a property. This implies that, in addition to your rent, you should deposit the difference between your rent and the estimated future mortgage payment into a savings account and treat it like any other monthly cost. This practice will accustom you to the idea of paying a bigger mortgage, and as an added plus, you’ll be saving for your home.Moreover, investing in stocks etc online on eToro review can help you save money.

  1. FIRST PAY YOURSELF

Before placing money into a savings account, many people wait until the end of the month to see how much money they have leftover. This is the very worst way to go about it since you will almost always find yourself with no money left over. If you want to begin serious about saving, you need the first to figure out how much money you have to put aside. It may take some getting used to, but once you start putting money away, you will begin to adjust. If you’re tempted to tap into your savings account, keep it in a separate bank from your checking account. To avoid temptation, we utilize an internet bank for our savings account, and many of them offer higher interest rates than traditional banks.

  1. CUT YOUR EXPENSES

If you’re wondering how and where to save money if you’re currently living paycheck to paycheck, start by cutting your costs by 10% across the board. That instance, if your monthly grocery budget is $500, consider cutting it by $50 for a total budget of $450. That’s not a big difference, but it adds up over time if you apply this strategy to all of your spendings. And before you know it, you’ll have enough money saved for a down payment. Just keep in mind that saving money takes time – it’s a marathon, not a sprint.

Thousands of Animals Will Be Saved Thanks To The #BettyWhiteChallenge

0

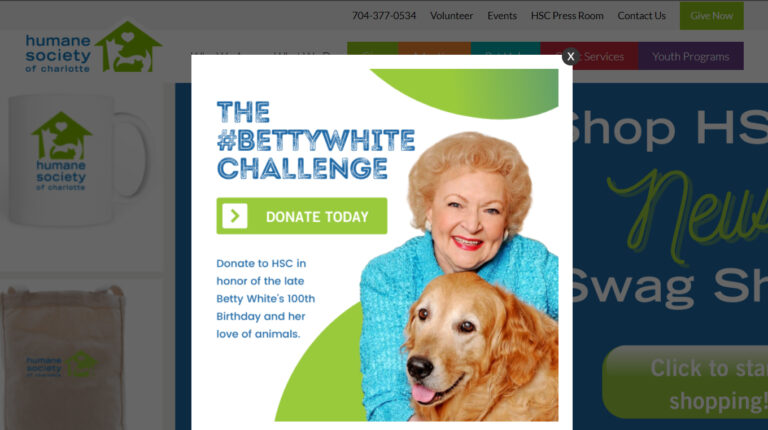
Today would have been America’s favorite Golden Girl’s 100th birthday. The late comedian and cultural icon passed away on December 31, 2021, just 17 days before her centennial milestone.

To honor her legacy and her passionate love for animals, the internet has decided to flood local animal shelters across the nation with funds in her honor.

The #BettyWhiteChallenge is now exploding in popularity, encouraging everyone to donate at least $5 to any local or national animal shelter, rescue or agency in Betty White’s name on Jan. 17th.

You can find out more about what the Humane Society of Charlotte does and easily give online on their website here.

Winter Storm Knocks Out Power For Tens of Thousands Across The Carolinas

0

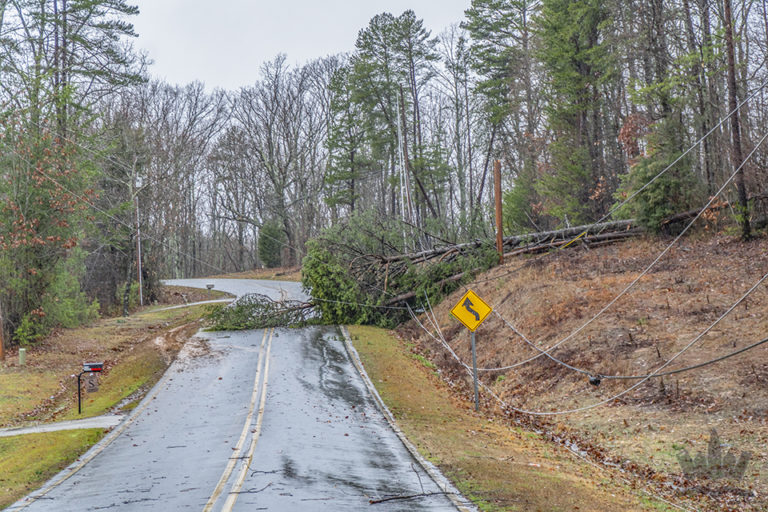
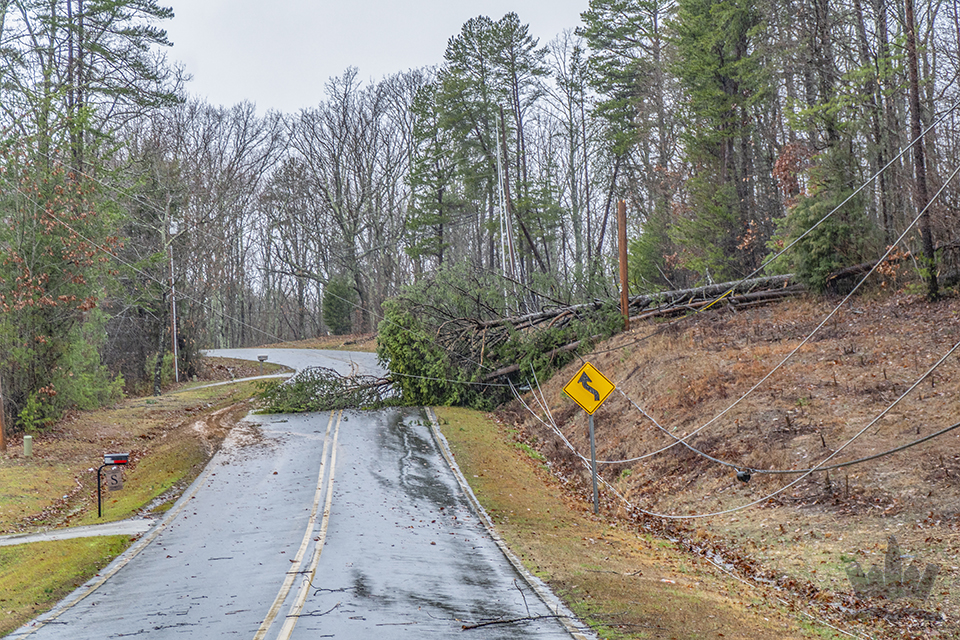
Yesterday’s Winter Storm Izzy not only brought freezing temperatures and iced over roads, the storm’s freezing rain and damaging winds also took down hundreds of trees and power lines across the Carolinas.

As of 9:20 this morning, there are still over 40,000 residents without power around our region, with most of them being located in northern South carolina.

Duke Energy reminded Carolina residents today to steer clear of any down power lines they might see – this includes trying to remove them from roads they are traveling down.

Did your power get knocked out during yesterday’s winter storm?

Déjà vu With Game Postponements

0

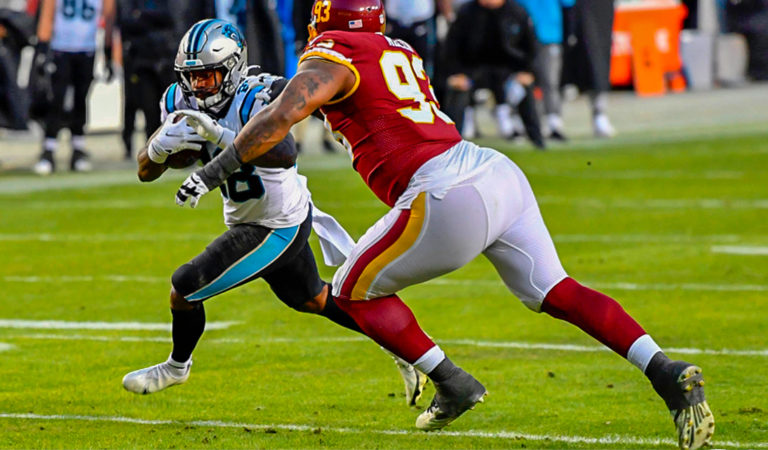
It’s safe to say it’s been an interesting couple of years for the biggest sporting events around the year, and despite things largely returning to normal with stadiums filling up with fans and odds for the latest options as punters. Check this site Oddsninja com for the best odds, it doesn’t seem the disruptions have come to an end just yet as a new round of postponements and cancellations have started, and some frustrating déjà vu for sporting fans hoping not to see any disruption to their sporting favorites.
Currently the UK seems to be the hub for these cancellations once more with outbreaks occurring in different football teams across the country, at first it was just a couple of Premier League games throughout early December, but that number quickly increased as it seems the rescheduled dates from the end of the year weren’t possible and heading into the new year even more games would need to be postponed for the time being. With documented protocols on how to handle rearrangement or postponement being quite rigid and only under “exceptional circumstances”, the rules have had to be adjusted in light of new factors that were starting to emerge once more primarily with safety and health at the forefront. 

Sporting in other parts of the world has seemingly been unaffected by the same issues, however – that isn’t to say that others may not see postponements in the near future but with different safety regulations and different decisions being made on what is needed as infections rise or fall, but it seems this approach is being actively avoided after what had been seen in the year prior. Delayed games and moving certain events into a bubble where entire seasons would only be played from one location certainly had an impact on ensuring that the same wouldn’t happen once again. 

With the worst impact of the global health crisis now seemingly in the past and the current approach leaning in towards more just dealing with the smaller outbreaks, a full scale return to normal will be the next step for sporting as a whole but caution will still need to be taken to ensure safety for not only fans but athletes too as there are still risks that will need to be measured and accounted for in the future too – at least for now it’s finally time to get back out there and start enjoying many of the biggest sporting events in stadiums once again, just incase the postponements do come back.

Financial Goals You Can Set for 2022

0

We are in 2022, and sadly, could not leave the pandemic behind in 2021. The Omicron strain seems to consolidate Covid-19 as the new virus that is here to stay, although with a limited level of lethality. The projections for this year speak of a more protected world, where restrictions will be, and vaccines will reach more corners, including sectors that distrust the traditional health system.

In economic terms, the global recovery is a fact, with consumption as the main driver. However, rising global inflation raises concerns and sets possible limits to growth, especially if it translates into a rate hike.

As we can see, the scenario is changing and forces us to modify our goals and strategies. It’s time to shuffle and give again to set new objectives in 2022.

Why Financial Planning Is Important

Saving for retirement, having control over our expenses and income, preparing the estate, having a cushion for contingencies, achieving an efficient payment of taxes, or saving with a specific objective are complex challenges. Still, they are even more so if we do not have adequate financial planning.  Because if you don’t do so, result might be a mountain of debt. But luckily, there are chapter 7 bankruptcy attorneys who can help you get your financial life back on track.

A financial plan is, neither more nor less, a compass that allows us to know where we want to go and where we are, indicating which is the shortest route and with minor obstacles to reach our destination.

Those who think financial planning is “a rich man’s thing” are entirely wrong. The truth is that high net worth will have some needs, while the most modest will have to face others. And they are as important as the others.

Keys To Get It Right

The starting point of all financial planning is, without a doubt, to make a conscientious analysis of the current situation and the goals that you want to achieve. If, for example, we want to plan our retirement, we must consider the moment in which we will start saving for retirement, the age at which we will foreseeably retire, and the life expectancy after that milestone.

Set clear and specific objectives. It isn’t easy to plan if we do not know what we are planning. If we do not prepare the stages of the trip well, we could arrive with our bag of provisions empty or, on the contrary, see how we have leftovers after having been hungry on the way.

Decide which is the best way to materialise our planning. There are so many alternatives, products, and information that it is vital to stop and reflect on the most appropriate for achieving our goals. We cannot ignore aspects of our financial profile, such as inflation, tax efficiency, and the advantages and disadvantages of each product.

The adaptation is essential as well. We evolve; our heritage and the circumstances surrounding us do not remain unchanged either. At each stage of our life, we ​​may need different things, and, therefore, it is not enough to draw a master plan on paper and wait for everything to go as planned. Towards the end, we’ll have to circumvent rocks and cut bridges, forcing us to make a detour.

Financial Planning for The Coming Year

Identify your financial goals to help you determine where you want to go and how to go about it. By setting your short, medium, and long-term goals, you can choose how to organise your savings.

Once you’ve figured out how much you wish to save, it’s time to think about how you’re going to do it. Consider the following planning strategies:

Short Term Goals

You should be able to easily access your funds for short-term goals within the following year. Consider keeping the money in a savings or money market account so that you can access these funds when you need them.

Planning: this is one of those magic words that everyone is tired of hearing and thinks he knows about everything. But not all companies, especially smaller ones, spend the time necessary to draw up strategies and achieve objectives and goals. Whenever we talk in the short term, impulsive decisions replace the action plan.

Short-term planning means formulating plans (courses of action) to achieve goals and objectives soon.

For this, it is necessary to evaluate the needs, demands and available resources to establish a strategy to implement an action and, later, to direct and control.

Medium Terms Goals

Your medium-term financial goals may be to buy a car, save for your child’s education, or repay your debt. You should reach your medium-term financial goals within five to seven years. Medium-term savings goals serve as a link between short-term and long-term financial goals.

Reasonable medium-term financial goals include:

  • Taking out insurance:

Life insurance acts as a lifeline for your dependents, whether you are the only member of your family making money or not.

In general, insurance premiums increase with age. Therefore, the sooner it is, the better. Easy term life insurance is sufficient, inexpensive, and if you die unintentionally, your family will be insured. The same is true for disability insurance. If you have a disability and cannot work, the insurance institution will replenish a portion of your income.

  • Chasing dreams:

We all have this “wish list” that we want to achieve someday. This list includes savings for family vacations, home repairs and refurbishments, savings for buying larger homes at significant destinations, savings for purchasing new cars, and more.

Risk Desire for Medium-Term Savings Goals

There is no room for risk in short-term financial goals, but the longer the target date for medium-term goals, the more risk you can take to achieve a larger savings plan. Investing over an extended time allows you to recoup any losses you may incur due to risky or unstable investments. That still doesn’t mean that you risk your six-month savings to buy your favourite blue-chip stock, as that is also a risky move.

Medium-Term Savings Target Option

Current Deposits: They are the safest option you can use, but unlike short-term financial savings options, we recommend that you do not consider short-term certificates of deposit. The shorter the period, the smaller the deposit.

Securities Accounts-Bonds are a safer option than stocks because of the limited time to recover. Investing in fixed income is considered safe, although earning income is limited.

Municipal Bond Funds-Municipal bond funds can be a good investment as their income is also tax-exempt.

Look for specific plans like these to earmark resources to achieve your medium-term goals

Long Term Goals

When you save for more than five years, you might consider other deposit or investment options to reach your goals. Investments that could offer a higher return could also be riskier. You must assess the balance between risk and return when making any investment decision.

A long-term financial goal is to save for more than ten years, or even life after retirement.

According to one study, you may need up to 85% of your pre-retirement income after retirement.

Your long-term goal is primarily your retirement. What is your retirement plan, and how do you want to retire? The answers to these questions form the foundation of long-term financial planning.

We often overlook short- and medium-term goals because long-term goals are not urgent. However, we recommend that you put 10-15% of your monthly income into the pension fund. It’s about harnessing the power of capitalising money over time to build a body big enough to fight inflation.

How Do You Assess Your Retirement Needs?

Calculate monthly costs after retirement. Budgets prepared in short-term financial plans can help.

Calculate all the income you will receive during your retirement. This calculation includes pensions, plan money, social security, and more.

The amount to be supplemented with long-term financial goals is total expenses minus total income.

Simply put, P = E-I

P is the amount covered by retirement savings.

E is the total cost incurred after retirement.

I is the income you will receive after retirement.

If you have enough time on your hands, you can take more risks if you feel like doing it. As you approach retirement, you can aggressively invest in high-margin investments, such as stocks and investment trusts, and switch to less risky investment options.

Where to invest a long-term savings fund:

Stock Market: There are risks associated with the stock market. However, stocks are more likely to have risk-adjusted returns, and the higher the risk, the more likely they are to be profitable. A long-term view means that investments are more likely to survive short-term market volatility.

Personal Retirement Account – Those who don’t have access to an employer-sponsored retirement plan can invest in an IRA. These plans provide tax-exempt or tax-exempt growth for retirement funds.

Venture capital funds or hedge funds: Wealthy individuals may want to consider options like hedge funds or hedge funds, which are high-risk investments but pay a lot.

Conclusion

For whatever strategy you choose, be sure to review your progress regularly to make sure you are on track. Following a savings plan is an intelligent strategy to achieve significant financial milestones.

Goal-based financial planning defines a roadmap for you to have all bases covered.

Once your goals are in place, keep reviewing and updating your goals according to the changing scenarios. Suppose you spend a decent portion of your emergency fund to pay medical bills or other emergency expenses – look for ways to replenish it and then look to revise the target if the original one seems unlikely.